
An Inflection Point
How AI can reshape insurance is something that’s been on my mind for months. It feels obvious. Insurance is one of the largest industries in the world, yet it still runs on practices that look more like 1996 than 2026.
Over the past few weeks alone, we've seen companies like Pace and Fulcrum announce major fundraising milestones alongside a steady stream of carrier press releases touting new “AI initiatives,” not to mention broker stocks plummeting amid growing uncertainty. On the surface, it looks like insurance might be having a moment again. But the more interesting part to me has come from conversations with carriers themselves.
I’ve spoken with underwriters, claims leaders, and data teams across large payors and brokers. Almost universally, there is a strong top-down push to “do something” with AI. Just as universally, the execution has been messy. One carrier described their current state as an “AI petting zoo” — contracting with four or five vendors for the exact same workflow and quietly admitting they have no idea what they're doing yet.
That begs the real question...is this just another fad vertical with a fresh coat of AI paint or is insurance actually on the cusp of producing durable, category-defining companies?
Why Insurance
- Premium growth is strong, but profitability is deteriorating: Global insurance premiums exceed $7T, up about 8.6% YoY. But much of this growth has been "bought" through rates in a volatile loss environment, not earned through efficiency. As combined ratios across certain lines push above 100, carriers are being forced to look inward at their own operating problems.
- Climate volatility and new risk classes are breaking old models: Global catastrophe losses are projected to reach their sixth straight year above $100B, with nearly 80% driven by U.S. events. At the same time, insurers are underwriting more cyber, supply-chain, and AI-liability risk where historical data is thin. In both cases, static models and manual underwriting workflows simply won't hold up.
- The labor model is quietly collapsing: The insurance workforce is aging out. A large share of underwriters, adjusters, and policy administrators are approaching retirement, while younger talent has shown limited interest in entering the industry. The result is a widening labor gap. Even if carriers wanted to solve this with people, they can’t.
Why Now
Insurance is fundamentally a paperwork business. Whether it's applications, endorsements, loss runs, adjuster notes, or bordereaux, most of the industry’s critical data lives in unstructured or semi-structured formats that traditional software has never handled well. Modern LLMs change that.
Even more importantly, we’ve crossed a second threshold with agentic AI. This shift turns AI into digital labor and that framing matters because the biggest budget pool in insurance isn’t IT, it’s operations, BPOs, TPAs, and internal service teams.
What the Market Is Missing
Despite all the noise, most carriers are still stuck with legacy systems like Guidewire, Duck Creek, and homegrown PAS / claims solutions that are rigid, poorly interoperable, and deeply manual. To compensate, firms like Patra, ResourcePro, and offshore TPAs are used to fill in the gaps.
Layer on top the growing collection of narrow AI pilots and you get the current state: fragmented tooling, duplicated effort, and very little confidence about what actually drives ROI. The reality is that insurance buyers don’t want a zoo of tools. They want a small number of dependable platforms.
From Systems of Record to Systems of Intelligence
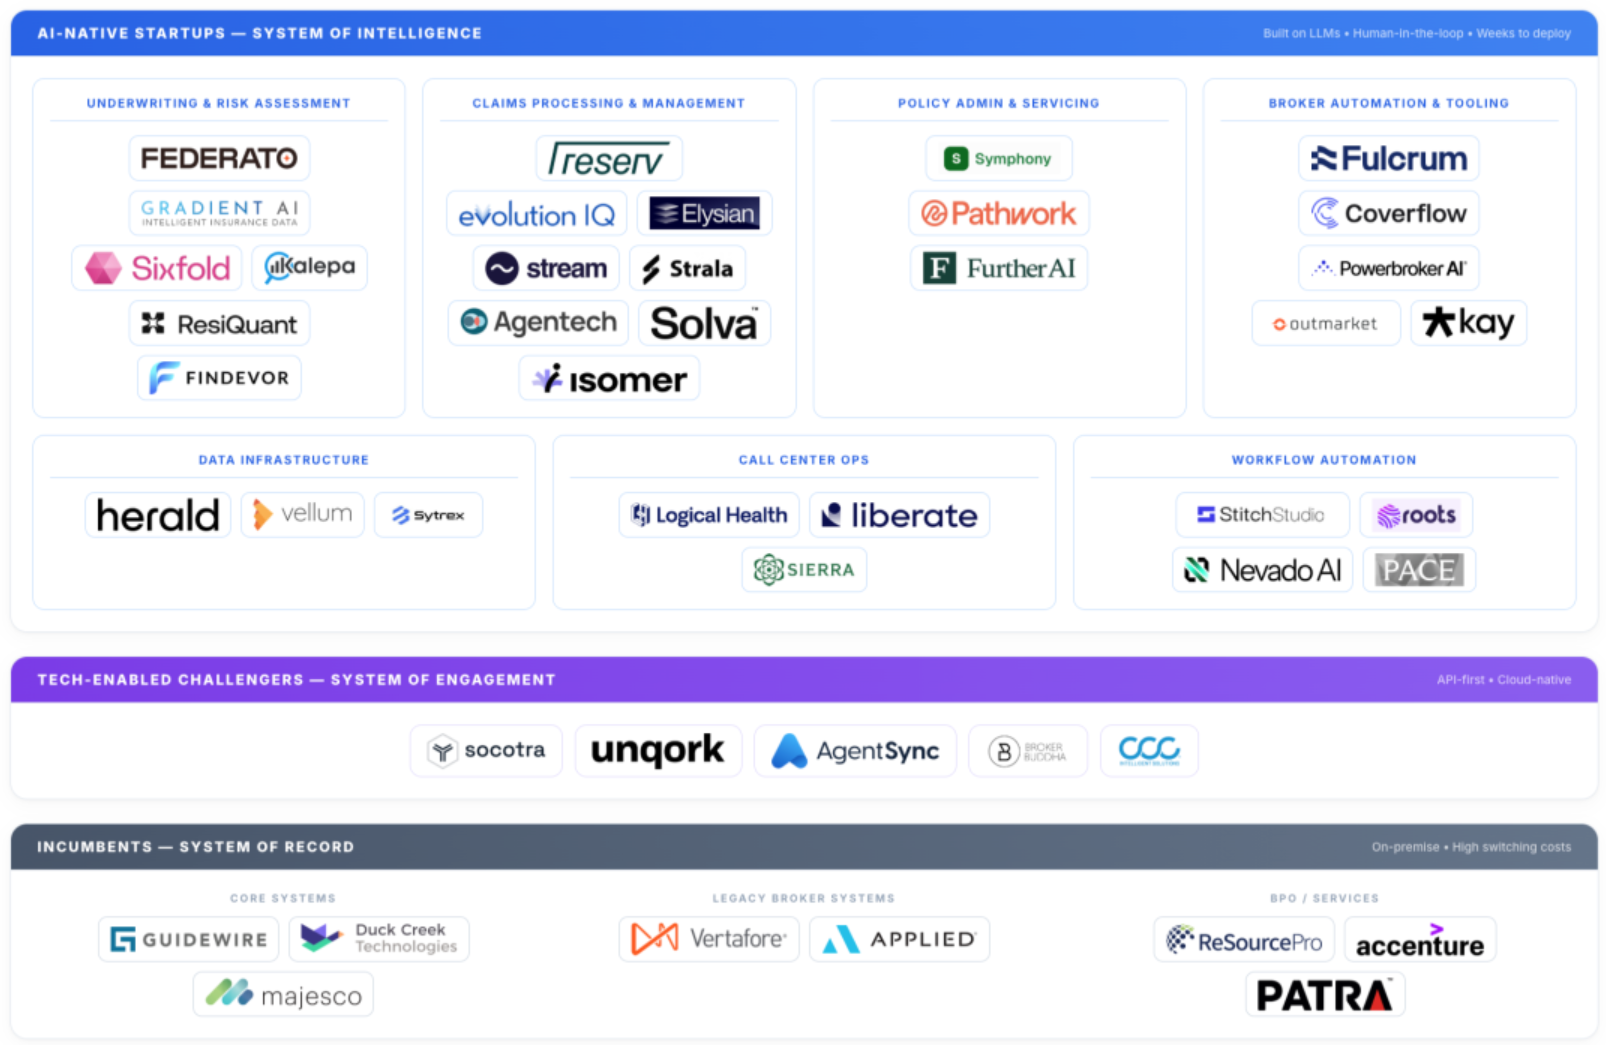
This is why I think the insurance stack is reorganizing into three layers:
- Systems of record: legacy cores like policy admin and claims systems that will remain the source of truth for now. They’re sticky, expensive, and slow to change.
- Systems of engagement: the prior wave of insurtech that improved UX and cloud adoption, but largely left cognitive labor untouched.
- Systems of intelligence: AI-native platforms that can reason over complex rules and execute independently.
In a fully realized AI-native insurance operation, agents handle 70–90% of end-to-end workflows, while human roles shift toward oversight, exceptions, and judgment. Every action is logged, explainable, and auditable for regulators and internal risk teams, creating transparency by design. Just as importantly, there is a clear line of sight to the P&L, allowing leaders to directly tie automation initiatives to combined ratio improvement and cycle-time reduction. This is why we are particularly excited by teams that pair deep insurance scars with real AI fluency.
Still, the most compelling opportunities aren’t always the obvious ones. While underwriting and claims triage are crowded, I'm especially interested in “boring,” high-complexity workflows like premium audit, subrogation, actuarial modernization, specialty E&S processes, and life & annuity back-office tasks.
Where Our Conviction Lies
At SemperVirens, our thesis rests on a few core beliefs:
- Digital labor beats standard SaaS. The winners in this category won’t sell seats. They’ll sell outcomes tied to volume, premium, or work performed.
- Vertical context is a moat, but not everywhere. Narrow-and-deep wins when talking high-risk, critical workflows. More generic functions like customer service call center operations and outbound engagement will likely be captured by strong horizontal players like Sierra or Decagon.
- Owning the data layer compounds. The first systems to structure the unstructured into an insurance-grade knowledge graph will become the new actuarial gold mines. Pricing improves. Portfolio management improves. Risk selection improves.
- Service-forward delivery helps, but with a path to scale. Selling into insurance is high-touch by default. The best teams embrace FDEs to land complex accounts, then systematically productize their learnings into a scalable, multi-tenant platform.
The Bottom Line
Insurance doesn’t need more point solutions. It needs a new operating layer. The carriers and brokers that pull ahead over the next decade won't be adopting AI simply as a feature, but will uproot existing workflows and deeply embed it, converging on a small number of trusted platforms.
The startups that win won’t rip out legacy systems overnight. They’ll sidecar onto them, earn credibility one business unit at a time, and quietly accumulate enough data and gravity to become indispensable.
Stay connected
Get our monthly newsletter to explore how we're building a world that works better.